Managing a Variable Income: How to Plan for a More Stable Budget
Managing a Variable Income: How to Plan for a More Stable Budget
For many Australians—freelancers, contractors, small business owners, and casual workers—a steady monthly income isn’t guaranteed. When your earnings fluctuate, it can be challenging to feel financially secure. But with the right planning, you can create stability and peace of mind, even when your income varies. Here’s how to build a more predictable budget and take control of your finances.
Know Your Average Income – and Plan Around It
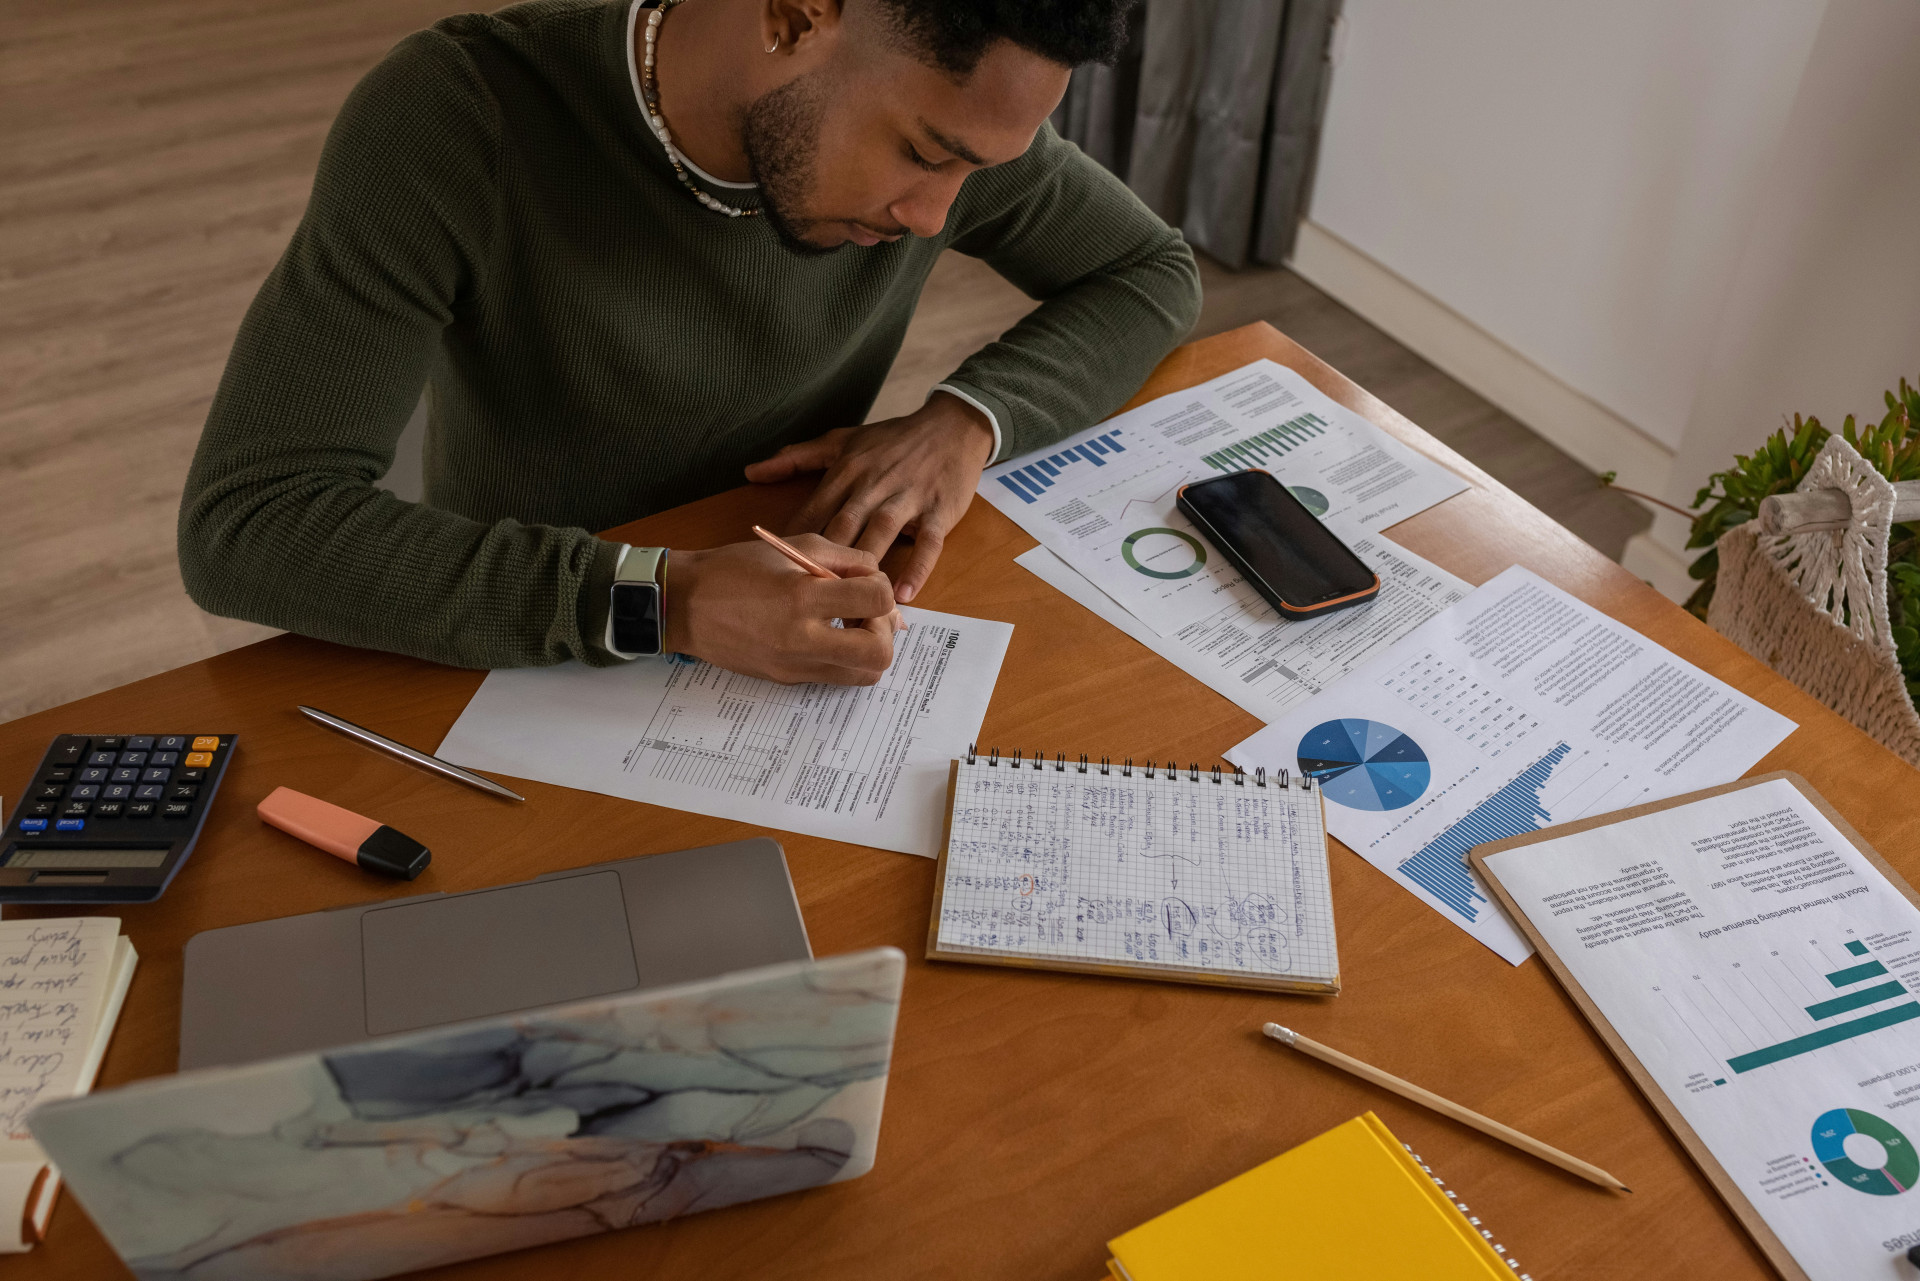
Start by understanding what you actually earn on average. Look back over the past year or two and calculate your average monthly income. This gives you a realistic picture of what you can expect and what you should base your budget on.
Once you know your average, create a base budget that reflects it. In months when you earn more, set aside the extra to cover expenses during quieter periods. This approach smooths out the highs and lows and helps you avoid financial stress when work slows down.
Build a Buffer Account
A buffer—or emergency fund—is your best defence against income swings. It acts as a safety net to cover essential expenses when your income dips.
Aim to save at least three to six months’ worth of living costs. That might sound daunting, but start small: each time you have a strong month, put aside a set percentage. Over time, your buffer will grow, giving you the confidence that you can handle leaner months without panic.
Læs også:
Separate Business and Personal Finances
If you’re self-employed or freelancing, it’s crucial to keep your business finances separate from your personal finances. This makes it easier to track what you truly earn and how much you can safely pay yourself.
Set up a regular “salary” from your business account to your personal account, based on your average profit. This creates a more stable household budget, even if your business income fluctuates. Keep the rest in your business account for tax, superannuation, and future expenses.
Use Technology to Stay on Top of Your Money
Digital tools can make managing a variable income much easier. Budgeting apps like Pocketbook, Frollo, or MoneyBrilliant can help you categorise spending, track cash flow, and set savings goals.
You can also automate transfers to your tax, super, and savings accounts. That way, money is set aside as soon as it comes in—reducing the temptation to overspend during good months.
Plan for Quiet Periods
Most industries with variable income have predictable patterns—busy seasons and slow ones. Use that knowledge to your advantage. If you know winter tends to be quieter, plan major expenses for the months when you expect higher income.
You can also use slower periods productively: update your portfolio, learn new skills, or reach out to potential clients. That way, downtime becomes an investment in your future earnings rather than a source of stress.
Stay on Top of Tax and Super
When you don’t have an employer handling your tax and superannuation, you need to manage them yourself. It’s tempting to put it off, but staying disciplined will save you headaches later.
Set up a separate tax account and transfer a percentage of every payment you receive—ideally a little more than you think you’ll need. This ensures you’re ready when your quarterly BAS or annual tax bill arrives.
Don’t forget your super contributions. Even small, regular payments into your super fund can make a big difference over time. Many Australian funds offer flexible options for self-employed workers, so it’s worth exploring what suits your situation.
Review Your Finances Regularly
When your income varies, regular check-ins are essential. Set aside time each month to review your numbers: what came in, what went out, and what’s coming up next.
By keeping a close eye on your finances, you can adjust early—before small issues become big ones. Over time, you’ll find that financial stability isn’t about earning the same amount every month, but about understanding and managing your cash flow.
Financial Stability Comes from Structure, Not Luck
Living with a variable income takes discipline, but it doesn’t have to be stressful. With an average-based budget, a solid buffer, and clear systems for tax, super, and savings, you can create stability even when your earnings fluctuate.
It’s not about predicting the future—it’s about being prepared for it. Once you have a structure in place, you’ll have the freedom to focus on your work and your goals, knowing your finances are under control.
Læs også: